
In the Monetary Policy Guidelines, the Bank of Russia each year describes the goals of monetary policy and approaches to its implementation and provides its view of the current situation in the economy and forecasts of its development in the medium term.
In 2025 H2–2026 H1, the gap between demand and supply in the Russian economy was narrowing gradually, which helped decelerate inflation. As underlying inflationary pressures weakened, the Bank of Russia was able to continue easing its monetary policy steadily. By the end of July 2026, the key rate was reduced to 14.00% p.a. from 21.00% p.a. in 2025 H1 (a total decrease of 7.00 pp). In September 2026, the Bank of Russia made a pause in cutting the key rate, given the intensified inflationary pressures, including in terms of underlying components, and increased proinflationary risks.
As one-off factors fade and driven by the monetary policy pursued, inflation will decelerate to 4% in 2027 and stabilise at the target further on.
Goal and principles
The goal of monetary policy is price stability, which is an essential condition for balanced and sustainable economic growth.
Low and stable inflation:
- Protects incomes and savings against unpredictable devaluation.
- Increases access to financing, through both credit and issuance of bonds and shares.
- Strengthens confidence in the ruble among households, businesses, and international partners.
- Improves the economy’s resilience to changes in the external environment.
Inflation targeting:
- Helps weather crises.
- Reduces the scale of a downturn or overheating in the economy.
- Is the world’s best practice, adopted by 47 countries and associations, with almost all of them maintaining a high or medium level of household incomes.
Monetary policy principles
- The target is an annual inflation rate of close to 4%. The target is effective on a permanent basis.
- The inflation rate is calculated by Rosstat based on the consumer price index (CPI).
- As part of its Monetary Policy Review to be completed in 2028, the Bank of Russia will analyse when the economy will be able to form the prerequisites for reducing the inflation target and to what level. If the Bank of Russia makes such a decision, it will be announced a few years before the change.
A floating exchange rate smooths out the impact of external factors on the economy and is an essential condition for efficient monetary policy.
- The Bank of Russia neither sets any targets for the level of the exchange rate or the pace of its movements nor conducts interventions for these purposes. Nevertheless, the Bank of Russia can perform operations in the FX market to maintain financial stability.
- Since 2022, the ruble exchange rate primarily depends on the ratio between importers’ demand for foreign currency and exporters’ supply of foreign currency.
- Capital flows still affect exchange rate dynamics, but their impact remains weaker than before 2022. The interest rate differential between Russia and other countries continues to influence the demand for investment in ruble assets and, as a result, the ruble exchange rate. Additionally, the exchange rate is affected by a number of structural factors.
- Capital controls are a policy instrument used solely for maintaining financial stability amid the sanctions and freezing of foreign currency accounts.
By setting the key rate and communicating its monetary policy decisions, the Bank of Russia forms such monetary conditions in the economy that help bring inflation back to the target and keep it at the target.
- The key rate and communication influence interest rates in the economy, securities prices and the ruble exchange rate, which in turn affect households’ and companies’ decisions on consumption, investment, saving, and ultimately, domestic demand in the economy and price dynamics.
- It takes three to six quarters for monetary policy decisions to fully translate into prices.
- The Bank of Russia’s communication includes forward guidance regarding possible further decisions on the key rate and its projected path.
Monetary policy decisions affect price dynamics with a time lag. Therefore, in making its monetary policy decisions, the Bank of Russia relies on a medium-term macroeconomic forecast, which is updated four times a year.
- When preparing the forecast, the Bank of Russia scrutinises a wide array of information and takes into account decisions related to other areas of state policy.
- Assessing risks over the forecast horizon, the Bank of Russia focuses more on proinflationary factors.
The Bank of Russia’s communication is aimed at enhancing society’s understanding of and confidence in the monetary policy stance. To this end, the Bank of Russia seeks to promptly and comprehensively communicate the information on the goals and principles of its monetary policy, economic developments and prospects, and the rationale for its decisions. The regulator is continuously working to make its communication more accessible and cover all target audiences.
The Bank of Russia’s monetary policy in late 2025 and 2026
Bank of Russia’s key rate and inflation
In 2025 H2–2026 H1, the gap between demand and supply was narrowing gradually under the influence of tight monetary policy. Credit activity was moderate, while households’ propensity to save was high. This limited the expansion of domestic demand. However, investment demand declined more significantly than consumer demand. Consumer activity was supported by fast growth in household incomes. Staff shortages were becoming less acute, but resources were still limited.
A more moderate increase in domestic demand helped alleviate underlying inflationary pressures. As of the end of 2025, annual inflation equalled 5.6%, which is its five-year low as of the end of the year. In 2026 H1, as assessed by the Bank of Russia, underlying inflation stayed within the range of 4–5% in annualised terms, while current price growth rates were fluctuating, driven by transitory factors.
The narrowing gap between demand and supply as well as the weakening of underlying inflationary pressures enabled the Bank of Russia to continue the monetary policy easing cycle started in June 2025. By the end of July 2026, the Bank of Russia cut the key rate by a total of 7 pp, from 21.00% p.a. to 14.00% p.a. Concurrently, the Bank of Russia maintained its monetary policy sufficiently tight to return inflation to the target.
In the summer months, inflationary pressures intensified again. The inflation spike was mainly attributable to rising prices for fuel, driven by a temporary reduction in its output. This one-off factor came to have a more extensive impact on prices through growing costs of companies and second-round effects associated with higher inflation expectations and demand. Underlying inflation accelerated to 5–6% in annualised terms. Additionally, a stronger fiscal impulse was expected in the medium term, as compared to the one assumed earlier.
In September, against the backdrop of rising price pressures and proinflationary risks, the Bank of Russia kept the key rate at 14.00% p.a. Further key rate decisions will depend on the dynamics of inflation and inflation expectations and the assessment of internal and external risks.
Forecast scenarios
Source: Bank of Russia.
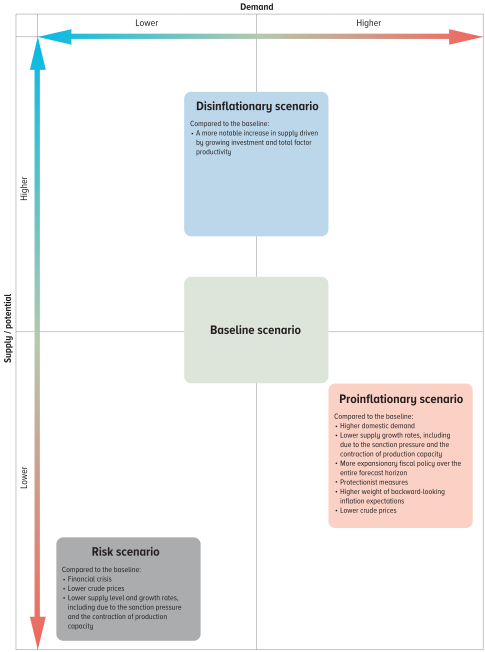
The Bank of Russia develops several scenarios with different assumptions regarding internal and external conditions to be able to make prudent decisions on monetary policy and be prepared for any changes. Whatever the scenario, monetary policy is aimed at ensuring an inflation rate of close to 4%.
Internal conditions:
- Structural transformation of the domestic economy.
- Fiscal policy parameters.
- Situation in the labour market.
- Dynamics of economic agents’ inflation expectations.
- Duration of the reduction in production capacity in certain industries.
- Protectionist measures.
External conditions:
- Dynamics of prices for main Russian exports.
- Inflation processes worldwide.
- Situation in global financial markets.
- Geopolitical conditions.
Baseline scenario
| 2025 (actual) |
2026 | 2027 | 2028 | 2029 | |
|---|---|---|---|---|---|
| Annual inflation, % | 5.6 | 6.0–7.0 | 4.0 | 4.0 | 4.0 |
| Key rate, yearly average, % p.a. | 19.2 | 14.5-14.6 | 10.5–12.5 | 8.0–9.0 | 7.5–8.5 |
| Gross domestic product, % YoY | 1.0 | 0.0–1.0 | 1.5–2.5 | 1.5–2.5 | 1.5–2.5 |
| — % change in Q4 YoY | 1.0 | 0.0–1.5 | 1.5–2.5 | 1.5–2.5 | 1.5–2.5 |
| Money supply (national definition), % YoY | 10.6 | 7–12 | 6–11 | 7–12 | 7–12 |
| Banking system claims on economy in rubles and foreign currency, % YoY, including: | 9.5 | 6–10 | 6–11 | 8–13 | 8–13 |
| ● on organisations | 11,9 | 7–11 | 7–12 | 8–13 | 8–13 |
| ● on households, including | 2.8 | 5–9 | 5–10 | 8–13 | 8–13 |
| – housing mortgages | 7.8 | 6–10 | 7–12 | 10–15 | 10–15 |
| Current account, $ bn | 39 | 48 | 25 | 15 | 10 |
| Financial account balance, net of reserve assets, $ bn | 44 | 43 | 36 | 25 | 16 |
| Net incurrence of liabilities | -5 | 15 | 7 | 8 | 9 |
| Net acquisition of financial assets, net of reserve assets | 39 | 59 | 42 | 33 | 25 |
| Change in reserve assets | -19 | -5 | -11 | -9 | -6 |
| Crude price for tax purposes, yearly average, $ per barrel | 56 | 60 | 50 | 50 | 50 |
The assumptions of the baseline scenario regarding economic developments in Russia and globally are the most probable in the Bank of Russia’s view.
Internal conditions:
- Economic growth will remain moderate in 2026, within the range of 0–1%, due to the temporary contraction of production capacity in certain industries, among other factors. In 2027–2029, the economy will be growing at a balanced rate of 1.5–2.5% per year.
- Investment activity will be increasing gradually, supported by inflows into restoration of production facilities and implementation of government investment and infrastructure projects. As interest rates go down, investment growth will accelerate.
- Consumer demand will continue to expand moderately, underpinned by rising household incomes. As interest rates decline, its contribution to economic growth will increase.
- The baseline scenario assumes that the federal budget’s structural primary deficit will decrease steadily from 2% of GDP in 2026 to 1% of GDP in 2027, 0.5% of GDP in 2028, and zero in 2029.
- Annual inflation will equal 6–7% in 2026. Its deviation from the target is largely attributable to the one-off factors, which emerged over the year, specifically tax and tariff changes and higher petroleum product prices. As a result of the monetary policy pursued, inflation will decelerate to 4% in 2027 and stay close to the target in the future.
External conditions:
- In 2026–2029, the world economy will be expanding by approximately 3% a year, which is below the 2000–2019 average.
- The conflict in the Middle East will cause a decline in global GDP growth and accelerate inflation worldwide.
- The rise in energy commodity prices, provoked by the conflict, will be temporary. As the situation normalises by early 2027 and OPEC+ and other countries expand their output, crude prices will adjust downwards.
- The sanctions imposed on Russia will remain and continue to hinder growth in Russian exports and imports and entail persistently elevated transaction costs.
| 2025 (actual) |
2026 | 2027 | 2028 | 2029 | |
|---|---|---|---|---|---|
| Annual inflation, % | 5.6 | 6.0–7.0 | 3.0–4.0 | 4.0 | 4.0 |
| Key rate, yearly average, % p.a. | 19.2 | 14.5-14.6 | 9.0 – 11.0 | 7.0–8.0 | 7.5–8.5 |
| Gross domestic product, % YoY | 1.0 | 0.0–1.0 | 2.5–3.5 | 2.0–3.0 | 1.5–2.5 |
| — % change in Q4 YoY | 1.0 | 0.0–1.5 | 2.0–3.0 | 2.0–3.0 | 1.5–2.5 |
| Money supply (national definition), % YoY | 10,6 | 7–12 | 8–13 | 8–13 | 7–12 |
| Banking system claims on economy in rubles and foreign currency, % YoY, including: | 9.5 | 6–10 | 8–13 | 9–14 | 8–13 |
| ● on organisations | 11.9 | 7–11 | 8–13 | 9–14 | 8–13 |
| ● on households, including | 2.8 | 5–9 | 8–13 | 9–14 | 8–13 |
| – housing mortgages | 7.8 | 6–10 | 10–15 | 11–16 | 10–15 |
| Current account, $ bn | 39 | 48 | 18 | 9 | 6 |
| Financial account balance, net of reserve assets, $ bn | 44 | 43 | 29 | 19 | 13 |
| Net incurrence of liabilities | -5 | 15 | 8 | 10 | 11 |
| Net acquisition of financial assets, net of reserve assets | 39 | 59 | 37 | 29 | 24 |
| Change in reserve assets | -19 | -5 | -11 | -9 | -6 |
| Crude price for tax purposes, yearly average, $ per barrel | 56 | 60 | 50 | 50 | 50 |
Compared to the baseline, productivity in this scenario will increase faster, while the economy’s production capacity will expand more substantially. This will enable the economy to grow faster without amplifying inflationary pressures, and as a result, the Bank of Russia will have more room for monetary policy easing.
Internal conditions:
- This scenario assumes a quicker rise in total factor productivity, compared to the baseline scenario, driven by more efficient resource distribution in the economy, deployment of advanced technologies, and implementation of earlier launched investment projects.
- As a result, potential output in 2027–2028 will expand faster than in the baseline scenario. Further on, the growth rate of potential output will return to its long-term range of 1.5–2.5%, but the achieved higher level of potential output will remain beyond the forecast horizon.
- Higher productivity will increase investment returns and make new investment projects more attractive. Domestic demand will be expanding more quickly than in the baseline scenario, driven by both consumption and investment.
- A quicker rise in labour productivity will enable real wages to grow at a high rate without leading to a notable increase in inflationary pressures.
- The fiscal policy-related assumptions are the same as in the baseline scenario.
- Inflationary pressures will be weakening more quickly and sustainably. Inflation will slow to 3–4% in 2027, which will allow the Bank of Russia to ease its monetary policy more considerably than in the baseline scenario.
External conditions:
- The assumptions regarding the world economy and the geopolitical environment are the same as in the baseline scenario.
| 2025 (actual) |
2026 | 2027 | 2028 | 2029 | |
|---|---|---|---|---|---|
| Annual inflation, % | 5.6 | 6.0–7.0 | 4.5–5.5 | 4.0 | 4.0 |
| Key rate, yearly average, % p.a. | 19,2 | 14.5-14.6 | 13.0–15.0 | 11.0–12.0 | 8.5–9.5 |
| Gross domestic product, % YoY | 1.0 | 0.0–1.0 | 1.0–2.0 | 0.5–1.5 | 1.5–2.5 |
| — % change in Q4 YoY | 1.0 | 0.0–1.5 | 0.5–1.5 | 0.5–1.5 | 1.5–2.5 |
| Money supply (national definition), % YoY | 10.6 | 7–12 | 8–13 | 7–12 | 7–12 |
| Banking system claims on economy in rubles and foreign currency, % YoY, including: | 9.5 | 6–10 | 4–9 | 6–11 | 6–11 |
| ● on organisations | 11.9 | 7–11 | 4–9 | 6–11 | 6–11 |
| ● on households, including | 2.8 | 5–9 | 4–9 | 6–11 | 6–11 |
| — housing mortgages | 7.8 | 6–10 | 5–10 | 8–13 | 8–13 |
| Current account, $ bn | 39 | 48 | 10 | 13 | 8 |
| Financial account balance, net of reserve assets, $ bn | 44 | 43 | 29 | 21 | 15 |
| Net incurrence of liabilities | -5 | 15 | 6 | 6 | 7 |
| Net acquisition of financial assets, net of reserve assets | 39 | 59 | 35 | 27 | 22 |
| Change in reserve assets | -19 | -5 | -19 | -8 | -7 |
| Crude price for tax purposes, yearly average, $ per barrel | 56 | 60 | 45 | 45 | 45 |
This scenario assumes that domestic demand will be higher and supply will be lower compared to the baseline scenario. Therefore, inflationary pressures will be higher, and the Bank of Russia will need to tighten its monetary policy to return inflation to the target.
This scenario is more likely than the disinflationary one.
Internal conditions:
- This scenario assumes the cooling in domestic demand to be less stable than in the baseline scenario due to a greater contribution of the fiscal impulse and a faster rise in incomes. The labour market will remain tight, while wages will be increasing much faster than labour productivity, thus amplifying the upward pressure on costs and prices.
- Investment activity will be more modest than in the baseline scenario, constrained by sanctions, high uncertainty, and labour costs. Production potential will be expanding more slowly due to a longer period needed to restore production facilities, a rise in associated maintenance costs, and tightening sanctions.
- Households’ and businesses’ inflation expectations will become more backward-looking and responsive to one-off price spikes.
- An expansion of protectionist measures will push up prices for imports and the demand for domestic products, thus putting additional pressure on prices.
- Inflation will slow to 4.5–5.5% in 2027 and return to the target later than in the baseline scenario. Although monetary policy cannot eliminate supply-side constraints, it will prevent inflation from accelerating persistently due to second-round effects and higher inflation expectations. The key rate will be higher. A more considerable contribution of fiscal policy to demand growth will also push up the longer-run neutral rate of interest.
External conditions:
- Increasing sanction pressure will limit access to technology and constrain growth in productivity and production potential.
- Russian crude prices, output, and exports will be lower than in the baseline scenario due to worsening geopolitical conditions and tightening sanctions.
| 2025 (actual) |
2026 | 2027 | 2028 | 2029 | |
|---|---|---|---|---|---|
| Annual inflation, % | 5.6 | 6.0–7.0 | 11.0–13.0 | 5.0–7.0 | 4.0 |
| Key rate, yearly average, % p.a. | 19.2 | 14.5 – 14.6 | 19.0 – 21.0 | 14.0 –16.0 | 9.5 – 10.5 |
| Gross domestic product, % YoY | 1.0 | 0.0–1.0 | (-4.0)–(-3.0) | (-2.5)–(-1.5) | 2.0–3.0 |
| — % change in Q4 YoY | 1.0 | 0.0–1.5 | (-9.0)–(-8.0) | 2.5–3.5 | 2.0–3.0 |
| Money supply (national definition), % YoY | 10.6 | 7–12 | 4–9 | 6–11 | 8–13 |
| Banking system claims on economy in rubles and foreign currency, % YoY, including: | 9.5 | 6–10 | 0–5 | 2–7 | 9–14 |
| ● on organisations | 11.9 | 7–11 | 2–7 | 3–8 | 9–14 |
| ● on households, including | 2.8 | 5–9 | (-5)–0 | (-1)–4 | 10–15 |
| – housing mortgages | 7.8 | 6–10 | 0–5 | 2–7 | 12–17 |
| Current account, $ bn | 39 | 48 | 5 | 4 | 9 |
| Financial account balance, net of reserve assets, $ bn | 44 | 43 | 11 | 17 | 13 |
| Net incurrence of liabilities | -5 | 15 | -5 | -1 | 2 |
| Net acquisition of financial assets, net of reserve assets | 39 | 59 | 6 | 16 | 16 |
| Change in reserve assets | -19 | -5 | -6 | -13 | -4 |
| Crude price for tax purposes, yearly average, $ per barrel | 56 | 60 | 35 | 25 | 30 |
A model-based assumption of this scenario is a sharp worsening of external conditions due to a possible global financial crisis. As a result, demand and supply will both decline in the Russian economy, although the decrease in supply will be more pronounced. This will provoke a notable acceleration of inflation, thus requiring a much tighter monetary policy stance.
The probability of this scenario is estimated as low.
External conditions:
- In this scenario, possible reasons for a global financial crisis include imbalances accumulated in advanced economies’ financial markets, large public debt, and rising long-term interest rates. A crisis might be triggered by a drastic revaluation of technology companies’ assets against the backdrop of heightened expectations regarding effects from the development of artificial intelligence.
- Global demand will plunge, and leading central banks will cut their policy rates.
- Crude prices will plummet and stay below the levels assumed in the baseline scenario until the end of the forecast horizon. Tighter sanctions will further reduce Russian crude output and exports and increase the discount for Russian crude.
Internal conditions:
- A steep drop in crude prices, tightening sanctions, and a longer-lasting reduction in production capacity will cause a decline in the Russian economy’s output potential and its growth rates. GDP will decrease in 2027–2028.
- To mitigate the fallout from the crisis in 2027–2028, the Government will expand fiscal support for the economy. Lower oil and gas revenues will require a more extensive use of the National Wealth Fund’s resources and changes in the fiscal rule parameters.
- Supply will contract more significantly than demand, causing inflation to accelerate sharply in 2027. The Bank of Russia will have to tighten its monetary policy substantially to bring inflation back to the target in 2029.
Use of monetary policy instruments
Money market rates
The operational objective of the Bank of Russia’s monetary policy is to keep overnight money market rates close to the key rate. The operational benchmark is RUONIA. To achieve its operational objective, the Bank of Russia employs a system of instruments (auctions and standing facilities to provide and absorb liquidity, and required reserves).
In 2026, the Bank of Russia has generally achieved the operational objective of its monetary policy. RUONIA mostly formed below the key rate, with the average spread equalling -27 bp in January–August. The spread volatility declined to 27 bp vs 37 bp in 2025.
In 2026 and over the entire three-year forecast horizon, banks’ demand for liquidity from the Bank of Russia will be rising. As money supply grows, the amount of cash in circulation and banks’ required reserves will also increase.
The Bank of Russia will continue to develop the system of monetary policy instruments. Among other things, in 2027, the regulator plans to synchronise the start date of required reserve averaging periods with the effective date of a new key rate level. This will help further decrease the volatility of money market rates.
Additionally, the Bank of Russia will continue creating a single collateral pool, establishing a separate urgent liquidity providing mechanism for financial market participants other than credit institutions, and exploring the issue of extending the operating hours of its payment system.
The Bank of Russia’s communication on monetary policy
Communication is another monetary policy instrument, in addition to the key rate. Monetary policy communication affects economic agents’ expectations and behaviours and thus enhances the efficiency of monetary policy.
- The purpose of communication is to improve the understanding of and confidence in the monetary policy pursued. This helps anchor inflation expectations and create a more predictable environment for making economic choices.
In 2026, the Bank of Russia was working to:
- Make its communication materials more transparent and clear. As a result of these efforts:
- the central bank transparency index (Al-Mashat’s methodology) rose from 11.9 to 12.4 points out of 20; and
- the Commentary on the Medium-term Forecast and analytical materials became more visual and accessible.
- Expand its direct engagement with businesses, the academic community, government authorities, and households, paying particular attention to feedback from them. Over January–August 2026, the Bank of Russia held:
- over 500 meetings with businesses in Russian regions; and
- more than 390 events in collaboration with universities.
- Enhance its communication via social media. As a result of these efforts:
- the total audience of the Bank of Russia’s and Financial Culture’s social media accounts exceeded 770,000 people; and
- standout media formats included a video podcast What is BoR Doing, a topical column #BoRanswers, and expert blogs about economic issues.
- In the future, the Bank of Russia will enhance its approaches to assessing the efficiency of its communication and tailor it to different audiences more accurately. Additionally, the regulator will explore how the development of artificial intelligence changes central bank communication.
Additional materials
Boxes
1. The level of the inflation target in Russia.
2. Benefits of a floating exchange rate.
3. Model-based approaches and their evolution.
4. Interaction of monetary and fiscal policies.
5. Monetary policy and financial sector stability.
6. The concept of a long-term economic equilibrium and deviations of key macroeconomic variables from it.
7. Quantitative analysis of reasons for the inflation deviation from the target and decomposition of GDP dynamics into shocks.
8. Factors determining the ruble exchange rate after 2022.
9. Fiscal policy in 2026–2029 and its impact on the economy.
10. Money market.
11. Economic agents’ inflation expectations.
12. The transfer curve and formation of interest rates on bank operations.
13. Subsidised lending and its impact on the transmission mechanism.
14. Assessment of the contribution of higher VAT to price growth.
Appendices
1. Monetary policy transmission mechanism in Russia.
2. Inflation measures used by the Bank of Russia.
3. One-off supply-side inflation factors.
4. Structural changes in the Russian economy.
5. Industry-level and regional analysis for monetary policy making.
6. Neutral interest rate and potential economic growth rates.
7. Financial market development.
Calendars and tables
Calendar of key rate decisions for 2027.
Monetary programme and liquidity forecast.